Private health insurance, explained in one phone call.
Paying for COBRA, working for yourself, or earning too much for Marketplace help? Talk with a licensed agent about private plans that may cost less, with every trade-off spelled out.
No cost, no obligation. Calls usually take about 10 minutes.
What your call covers
- Length
- About 10 minutes, by phone
- Cost
- Free, with no obligation to buy
- You'll get
- Plan options that fit your health, budget, and doctors
- With
- Jovon Stewart, licensed agent
- Available
- Most U.S. states
Built for people buying their own coverage
These plans are a good fit for some people and the wrong fit for others. Here's who usually benefits most.
You left a job and COBRA is expensive
COBRA keeps your old plan, but you now pay the full premium yourself, often several hundred dollars a month or more.
If you're in good health, a private plan may cover what you actually use for less. We'll compare it side by side with what you pay now, so you can decide with real numbers.
Don't cancel COBRA until your new plan is approved and active. We'll make sure there's no gap.
You're self-employed or a business owner
No employer plan, and every dollar of premium comes out of your own pocket. You want coverage that matches how you actually use healthcare.
Your income is over the subsidy limit
If your household earns above the Marketplace subsidy cutoff, you pay full price there. Private plans are worth comparing before open enrollment.
Private plans also work well if you're
Turning 26
Coming off a parent's plan and buying coverage for the first time. Premiums at this age are often low.
A gig worker or contractor
Rideshare, real estate, the trades, beauty, fitness. If you get a 1099 instead of a W-2, you're buying your own coverage.
Retired early and not yet 65
Coverage to carry you until Medicare starts. Approval depends on health, so we'll check eligibility early in the call.
Between jobs
Waiting for a new employer's coverage to begin? Temporary options are available in many states to bridge the gap.
How it works
No forms to figure out on your own and no automated quotes that leave out the details.
Pick a time
Choose a slot that works for you and answer a few quick questions so the call is about your situation.
Talk it through
We go over your health, budget, and doctors, then walk through options from national carriers in plain English.
Decide on your terms
If a plan fits, I help you apply. If nothing fits, I'll tell you that too. There's no pressure either way.
What to know before you call
You should understand these points before buying any plan, from me or anyone else.
Plans are medically underwritten
You answer health questions on the application, and approval depends on your answers. These plans generally work best for people in good health.
Pre-existing conditions may not be covered
Many private plans limit or exclude conditions you had before coverage started, usually for a set period. We'll go over the exact rules for each plan.
Some plans pay fixed amounts
Fixed indemnity plans pay a set dollar amount per service, not a percentage of your bill. They are not major medical coverage and don't replace an ACA plan.
Not offered in every state
Plans aren't currently available in Alaska, Massachusetts, New Hampshire, New Jersey, New Mexico, New York, Oregon, or Washington. Options vary by state.
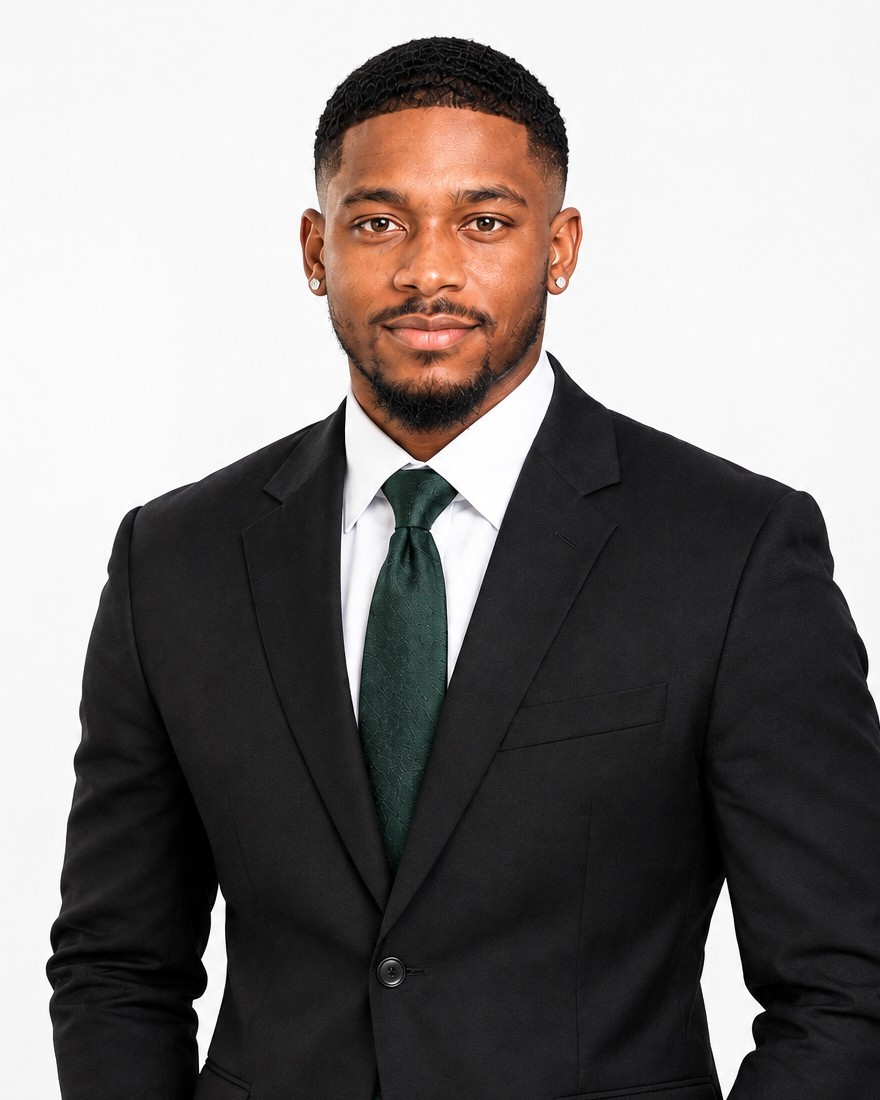
Hi, I'm Jovon
I'm a licensed health insurance agent, and I started Keypoint Health Solutions because buying your own coverage shouldn't feel like a guessing game. My job is to explain your options clearly, including what a plan doesn't cover, so you can make a decision you won't regret later.
I work with multiple national carriers, so I can compare options instead of pushing one company's plan.
Book your free call
Pick a time below. You'll get a confirmation right away and a reminder before we talk.
- About 10 minutes
- No cost and no obligation
- Have a rough idea of your household income and any current coverage